On this page
- 1. Start with the two penalty questions
- 2. How the Part B late enrollment penalty works
- 3. Why VA health care does not replace Medicare enrollment
- 4. TRICARE For Life requires Parts A and B
- 5. Know your Medicare enrollment windows
- 6. Part D follows a different rule for many veterans
- 7. IRMAA is a surcharge, not a late enrollment penalty
- 8. If a penalty notice looks wrong
- 9. Programs that may help with Medicare costs
- 10. A practical checklist before you delay Part B
- 11. Key takeaways for veterans
- 12. Continue the field guide
- Common questions
- Sources
Key points
- VA health care does not create the current-employment Special Enrollment Period that can let someone delay Part B without a late enrollment penalty.[1][2]
- The Part B late enrollment penalty is generally 10% for each full 12-month period without Part B when you could have enrolled, and it usually lasts as long as you have Part B.[3]
- TRICARE For Life requires Medicare Parts A and B; Part C and Part D are not required for TFL eligibility.[4][5]
- VA and TRICARE prescription coverage can be creditable for Part D, but keep coverage records and act within 63 days if that coverage ends.[6][1]
- IRMAA is an income-related surcharge, not a late enrollment penalty; a life-changing event may support an appeal through Social Security.[7][8]
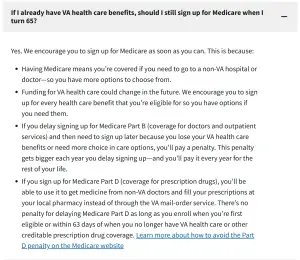
The most important distinction in this chapter is simple: VA health care can coexist with Medicare, but it is not a substitute for enrolling in Medicare Part B when your enrollment window arrives. VA and TRICARE prescription coverage are a different question because they may count as creditable coverage for Part D. Your exact timing depends on your age, current employment, and other coverage, so use the official rules rather than a general assumption.[1][3][6]
If you are turning 65 with VA health care, check your Medicare Part A and Part B enrollment options during your Initial Enrollment Period. If you are still covered by a current employer group plan, ask whether a Special Enrollment Period applies. If you have TRICARE For Life, Parts A and B are required. A Medicare enrollment decision should be coordinated with Social Security, Medicare, VA, or TRICARE for your specific situation.
1. Start with the two penalty questions
Medicare penalties are not one single rule. Part B concerns medical and outpatient coverage. Part D concerns prescription drug coverage. The coverage that protects you for one part may not protect you for the other.
| Coverage | Question to ask | Veteran-specific point |
|---|---|---|
| Part B | Did I have Medicare or qualifying current-employment group coverage when I could have enrolled? | VA health care by itself is not the current-employment coverage described for the Part B Special Enrollment Period.[2][1] |
| Part D | Did I have creditable prescription drug coverage without a gap of 63 days or more? | VA and TRICARE drug coverage are listed as creditable coverage, subject to keeping that coverage and responding if it ends.[6] |
| TRICARE For Life | Do I have both Medicare Part A and Part B? | TFL requires A and B. Part C and Part D are not required for TFL eligibility.[4][5] |
This table is a starting point, not an enrollment determination. Medicare, Social Security, VA, and TRICARE can confirm the rule that applies to your record.
2. How the Part B late enrollment penalty works
Medicare.gov says the Part B late enrollment penalty is an extra 10% of the standard Part B premium for each full 12-month period you could have had Part B but did not. The penalty usually continues for as long as you have Part B. A qualifying Special Enrollment Period or a Medicare Savings Program can change the outcome.[3]
The dollar amount is not fixed because the percentage is applied to the current Part B premium. The standard Part B premium is $202.90 for 2026; higher-income beneficiaries may owe more. This is a 2026 figure, not a projection of a future premium.[9][10][7]
- One full 12-month period without Part B can mean a 10% penalty.
- Three full 12-month periods can mean a 30% penalty.
- Five full 12-month periods can mean a 50% penalty.
- The calculation uses the applicable current Part B premium, and Medicare applies its rounding rules.[3]
| Full 12-month periods delayed | Part B late enrollment percentage | What changes |
|---|---|---|
| 0 | 0% | No Part B late enrollment percentage from this rule |
| 1 | 10% | An additional 10% of the applicable standard premium |
| 3 | 30% | An additional 30% of the applicable standard premium |
| 5 | 50% | An additional 50% of the applicable standard premium |
This table shows the formula, not a promise about a particular person's bill. Eligibility, Medicare Savings Programs, income-related amounts, and rounding can affect the final premium.[3][9]
For a quick estimate, you can use the site's Part B Penalty Calculator, then confirm the result with Medicare or Social Security. A calculator is an estimate; it cannot decide whether your past coverage qualified.
3. Why VA health care does not replace Medicare enrollment
VA explains that having other health insurance does not determine whether you can receive VA health care, and it encourages eligible veterans to sign up for Medicare. Medicare can provide another route to care at a non-VA hospital or doctor, while VA health care remains a separate system. VA also says you choose which benefits to use each time you receive care; VA and Medicare do not pay for the same item or service.[1][11]
VA community care is also not a general replacement for Medicare enrollment. Community care must be authorized by VA before a veteran receives care from a community provider, subject to the program's rules.[12]
If you have CHAMPVA and become eligible for Medicare, VA says you must have both Part A and Part B to get or keep CHAMPVA; a Medicare Advantage plan can also meet that requirement.[13]
4. TRICARE For Life requires Parts A and B
TRICARE For Life is wraparound coverage for people who are TRICARE-eligible and have Medicare Part A and Part B. You must keep paying the Part B premium to keep Part B, and TFL is not a reason to skip Part B. You do not need Medicare Part C or Part D for TFL eligibility.[5][4]
- Confirm that you are enrolled in Medicare Part A and Part B before TFL is expected to begin.
- Plan for the Part B premium and check that Medicare has your correct address and enrollment information.
- If both programs cover a service, Medicare generally pays first and TRICARE pays last; services covered by only one program can have different cost-sharing rules.[5]
- If you choose a Medicare Advantage plan, use that plan's network for nonemergency care, expect that copayments may apply, and understand that paper claims to TRICARE may be needed.[4]
The TRICARE For Life and Medicare guide explains coordination in more detail. Because plan networks and claims procedures can change, check TRICARE's current instructions before an appointment.
5. Know your Medicare enrollment windows
The safest enrollment window is usually the Initial Enrollment Period unless you have a qualifying reason to use a Special Enrollment Period. Medicare and Social Security should confirm the dates for your situation.
Initial Enrollment Period: the seven-month window
- It begins three months before the month you turn 65.
- It includes your birthday month.
- It ends three months after the month you turn 65, for a total of seven months.[2]
- Coverage start dates depend on when you enroll. If your birthday is on the first day of the month, Medicare coverage can start the month before your birthday month.[2]
If you are already receiving Social Security benefits at least four months before turning 65, Medicare says you may be automatically enrolled in Parts A and B. Otherwise, Social Security explains how to sign up.[14]
Special Enrollment Period: current employment matters
A Part B Special Enrollment Period is generally tied to coverage from current employment for you or your spouse. COBRA and retiree coverage do not create that employment-based SEP. Medicare says the SEP generally lasts eight months after the employment or qualifying group coverage ends, but your exact dates should be confirmed before you delay enrollment.[2]
- Ask the employer or benefits administrator whether the coverage is group health coverage from current employment.
- Do not treat VA health care, VA community care, COBRA, or retiree coverage as a current-employment SEP without confirmation.[2][1]
- Keep proof of coverage and the dates you or your spouse were actively working.
General Enrollment Period: a later route
Medicare's General Enrollment Period runs January 1 through March 31 each year. If you use it after missing an earlier window, a late enrollment penalty may apply and coverage generally begins after enrollment. Check the current start-date rule before making a decision.[15][2]
6. Part D follows a different rule for many veterans
Medicare lists prescription drug coverage from the Department of Veterans Affairs and TRICARE among examples of creditable prescription drug coverage. Creditable means the coverage is expected to pay, on average, at least as much as standard Medicare drug coverage.[6]
- Keep your VA or TRICARE drug-coverage notices and enrollment records.
- If that creditable drug coverage ends, ask about a Part D Special Enrollment Period promptly; Medicare uses a 63-day gap rule.[6][1]
- Do not assume that VA medical coverage and VA prescription coverage have the same Medicare effect.
- If you join a Medicare drug plan, answer its questions about prior creditable coverage accurately.
The VA health care and Medicare guide covers the practical coordination questions that sit behind this distinction.
7. IRMAA is a surcharge, not a late enrollment penalty
The Income-Related Monthly Adjustment Amount, or IRMAA, is an income-related surcharge added to Medicare Part B and Part D premiums for some higher-income beneficiaries. It is separate from a late enrollment penalty. Social Security generally uses tax information from two years earlier; for 2026, the relevant tax year is generally 2024, and the first income thresholds are $109,000 for single filers and $218,000 for joint filers.[7][8]
- A pension distribution, property sale, or Roth conversion can affect the tax return used for the later IRMAA determination.
- VA disability benefits administered by VA are generally not included in federal gross income, but other income can still affect MAGI; ask a qualified tax professional about your return.[16][7]
- If your income fell because of a qualifying life-changing event, Social Security's IRMAA appeal process may apply. Form SSA-44 is the starting point described by SSA.[8]
For a deeper explanation, see the site's IRMAA guide. Do not label an IRMAA determination as a Part B late enrollment penalty; the records and appeal path are different.
8. If a penalty notice looks wrong
Read the notice carefully and compare it with your Medicare enrollment dates, employment dates, and coverage records. If the notice concerns employment-based coverage, ask the employer or benefits administrator for written dates and contact Social Security for the official review process. If the issue concerns VA or TRICARE, ask that agency to confirm the coverage dates and type as well.
- Collect the timeline Write down your 65th-birthday month, when you stopped working, when group coverage ended, and when Part A or Part B began.
- Separate the coverage type Identify whether the disputed months involve current-employment group coverage, VA health care, TRICARE, COBRA, retiree coverage, or prescription coverage.
- Send records through the official channel Use the instructions on the notice and keep copies of forms, employer statements, coverage notices, and delivery confirmations.
- Ask before changing coverage Do not drop VA, TRICARE, employer, or Medicare coverage while a question is unresolved. Confirm the effect with the agency that administers the coverage.
9. Programs that may help with Medicare costs
Medicare Savings Programs are state-administered programs that may help eligible people pay Part B premiums and, for some programs, other Medicare cost-sharing. Income and asset rules apply, and the rules can change. Medicare says to apply through your state even if you are not sure you qualify.[17]
QMB
May help with Part A and Part B premiums and certain Medicare deductibles, coinsurance, and copayments for people who meet the program rules.[17]
SLMB
May help eligible people with the Part B premium.[17]
QI
May help eligible people with the Part B premium, subject to program funding and state rules.[17]
For an application, contact your state Medicaid office or State Health Insurance Assistance Program. Medicare's official Medicare Savings Programs page has the current eligibility information and instructions.[17]
10. A practical checklist before you delay Part B
- I know whether I am in my seven-month Initial Enrollment Period.
- I have asked whether current employment coverage, for me or my spouse, creates a Part B Special Enrollment Period.
- I am not treating VA health care, VA community care, COBRA, or retiree coverage as current-employment coverage without confirmation.[2][1]
- If I have TRICARE For Life, I have a plan for Medicare Parts A and B and the Part B premium.[5]
- I know whether my prescription coverage is creditable and where its records are stored.[6]
- I have checked whether an income change could affect IRMAA and know where to ask about an appeal.[8]
- I have written down the questions I will ask Medicare, Social Security, VA, TRICARE, or my employer benefits office.
11. Key takeaways for veterans
- Part B and Part D have different late enrollment rules.
- VA health care does not replace the need to evaluate Medicare Part B enrollment.[1][3]
- VA and TRICARE prescription coverage can protect against a Part D late enrollment penalty when it remains creditable.[6]
- TRICARE For Life requires Parts A and B, while Part C and Part D are not required for TFL eligibility.[4]
- IRMAA is an income-related surcharge and should not be confused with a late enrollment penalty.[7]
- When your situation is unusual, get the coverage administrator's answer in writing before you delay or drop coverage.
12. Continue the field guide
This chapter is designed to help you prepare better questions, not to replace an enrollment decision from Medicare or Social Security. Continue to the complete Medicare field guide, or start with the Veterans Medicare FAQ for related answers. For a coverage-specific conversation with Veterans Advantage Financial®, you can book a call or call 888-960-8387.
Common questions
Does VA health care protect me from a Part B late enrollment penalty?
VA health care alone is not the current-employment group coverage used for the Part B Special Enrollment Period. Check your Initial Enrollment Period and confirm your circumstances with Medicare or Social Security.[1][2][3]
Do I need Medicare Part B for TRICARE For Life?
Yes. TRICARE For Life requires Medicare Parts A and B, and you must keep paying the Part B premium. You do not need Part C or Part D for TFL eligibility.[5][4]
Does VA prescription coverage count for Part D?
Medicare lists VA and TRICARE prescription drug coverage as examples of creditable coverage. Keep proof of coverage and ask about the 63-day rule if that coverage ends.[6][1]
What is the 2026 standard Part B premium?
The standard Part B premium is $202.90 for 2026. Some people pay more because of income-related amounts, and a late enrollment penalty can also change the bill.[9][10][7]
Can an income change affect IRMAA?
Yes. Social Security may allow an IRMAA appeal after certain life-changing events, using Form SSA-44 and supporting documentation.[8]
Sources
- U.S. Department of Veterans Affairs. “VA health care and other insurance.” VA.gov, last updated July 14, 2025. va.gov/resources/va-health-care-and-other-insurance
- Medicare.gov. “When does Medicare coverage start?” medicare.gov/basics/get-started-with-medicare/sign-up/when-does-medicare-coverage-start
- Medicare.gov. “Avoid late enrollment penalties.” medicare.gov/basics/costs/medicare-costs/avoid-penalties
- TRICARE (Defense Health Agency). “Q&A: How does TRICARE For Life work with Medicare?” TRICARE Newsroom, December 14, 2023. newsroom.tricare.mil/News/TRICARE-News/Article/3617884/qa-how-does-tricare-for-life-work-w
- TRICARE (Defense Health Agency). “TRICARE For Life.” TRICARE.mil, last updated September 25, 2026. tricare.mil/tfl
- Medicare.gov. “Creditable prescription drug coverage.” medicare.gov/health-drug-plans/part-d/basics/creditable-coverage
- SSA.gov. Premiums: rules for higher-income beneficiaries ssa.gov/benefits/medicare/medicare-premiums.html
- SSA.gov. Lower your IRMAA ssa.gov/medicare/lower-irmaa
- Centers for Medicare & Medicaid Services. “2026 Medicare Parts A & B Premiums and Deductibles” (fact sheet), November 14, 2025. cms.gov/newsroom/fact-sheets/2026-medicare-parts-b-premiums-deductibles
- Medicare.gov. “Medicare costs.” medicare.gov/basics/costs/medicare-costs
- Medicare.gov. “Who pays first?” (coordination of benefits). medicare.gov/health-drug-plans/coordination/who-pays-first
- U.S. Department of Veterans Affairs. “Community care: Veteran care overview.” VA.gov. va.gov/communitycare/programs/veterans/index.asp
- U.S. Department of Veterans Affairs. “CHAMPVA benefits.” VA.gov, last updated August 7, 2026. va.gov/family-and-caregiver-benefits/health-and-disability/champva
- Medicare.gov. How do I sign up for Medicare? medicare.gov/basics/get-started-with-medicare/sign-up/how-do-i-sign-up-for-medicare
- Medicare.gov. “Joining a health or drug plan.” medicare.gov/basics/get-started-with-medicare/get-more-coverage/joining-a-plan
- IRS.gov. Publication 525, Taxable and Nontaxable Income irs.gov/publications/p525
- Medicare.gov. “Medicare Savings Programs.” medicare.gov/basics/costs/help/medicare-savings-programs
Sources checked October 11, 2026. Dollar amounts are for 2026 unless noted.
This is general education, not personal advice, and it isn’t a recommendation of any specific plan. Veterans Advantage Financial® is a licensed insurance agency, not affiliated with or endorsed by Medicare, Social Security, VA, TRICARE or any government agency. Plan availability, costs and benefits vary by plan, county and year. Check your own situation with the agency or plan before making changes.

Christopher Duncan
Christopher founded Veterans Advantage Financial® and has helped people with Medicare since 2006. He is a licensed insurance agent in all 50 states and DC (NPN 8613503). His dad, Wallace, is a Vietnam-era veteran.