
Veterans Advantage Financial®
Medicare for Veterans | Fixed Annuities | Retirement Income | Veterans Only
We Speak Veteran®
Lock In Your 5-6% Guaranteed Rate Today
888-960-VETS(8387)Fixed Annuity for Veterans: Understand MYGA Terms and Guarantees
Fixed annuity for veterans can offer a stated fixed interest rate for a contract period; liquidity and contract value can still be affected by withdrawals, surrender charges, market value adjustments, and the issuing insurer's claims-paying ability. Furthermore, as a veteran, you've earned the right to secure retirement income through MYGA for veterans and veterans guaranteed annuity products. Additionally, Multi-Year Guaranteed Annuities provide fixed annuity rates veterans can count on - 5-6% returns that beat traditional CDs. Moreover, this tax deferred annuity veterans choose most allows your money to grow without annual tax bills.
Why Veterans Choose Fixed Annuities (MYGAs)
Veterans seeking a fixed annuity for veterans find MYGAs ideal for retirement planning. However, these products offer more than just predictable returns. In fact, principal protection combined with competitive interest rates makes MYGAs particularly attractive for conservative investors. Subsequently, many veterans discover that MYGAs provide the security they want without sacrificing growth potential.
Key Benefits of Veteran Fixed Annuity:
- ✅ Contract rate shown in the illustration - Compare with CDs and other options
- ✅ Tax-deferred growth - Keep more of your earnings
- ✅ Fixed interest and contract guarantees - Review liquidity limits, charges, adjustments, and insurer claims-paying ability
- ✅ Flexible terms - Choose 3, 5, 7, or 10-year periods
- ✅ 10% annual withdrawal - Access funds without penalties
Illustrative MYGA Rates Shown as of December 2025 — Not Current
These figures are illustrative examples shown as of December 2025—not current offers. Verify today's rate, issuing insurer and product, term, minimum premium, surrender schedule, any market value adjustment, and state availability before relying on them:
| Term Length | Current Rate | Minimum Deposit |
|---|---|---|
| 3-Year MYGA | Illustrative — verify current rate | $10,000 |
| 5-Year MYGA | Illustrative — verify current rate | $10,000 |
| 7-Year MYGA | Illustrative — verify current rate | $10,000 |
| 10-Year MYGA | Illustrative — verify current rate | $10,000 |
Rates effective December 2025. Subject to change and state availability.
Tax-Deferred Annuity Veterans Love: The MYGA Advantage
A tax deferred annuity veterans choose most is the MYGA. Unlike CDs, your interest compounds without annual tax bills. As a result, this means more money stays invested and working for you. Furthermore, when comparing a tax deferred annuity veterans select versus taxable investments, the difference in returns can be substantial over time.
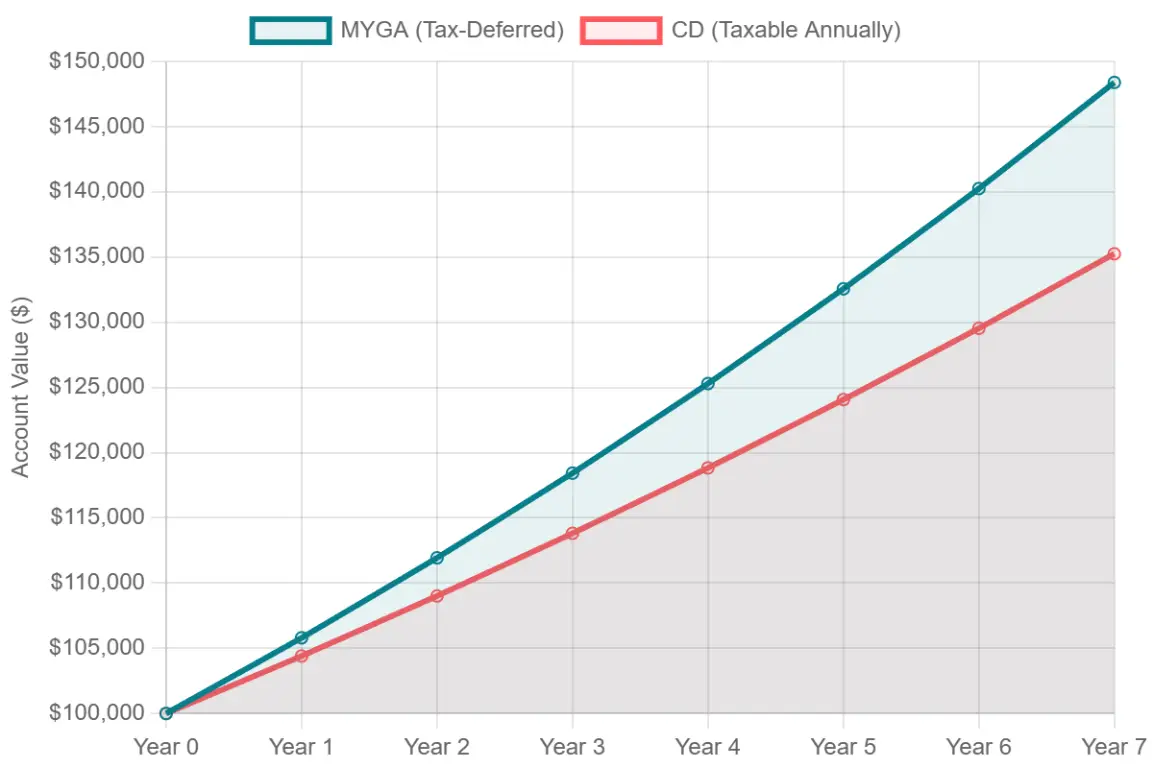
MYGA for Veterans vs. Bank CDs
Veterans comparing a MYGA for veterans to traditional CDs find clear advantages. First, MYGAs may compare differently with bank products depending on the dated offer, term, liquidity, taxes, and guarantees. Annuities are not FDIC/NCUA deposits. State life-and-health guaranty associations may provide limited protection after an insurer insolvency, subject to the resident state's statutes, coverage limits, exclusions, and contract status; this is not equivalent to FDIC insurance. No product is best for everyone.
How Fixed Annuities Complement Your VA Benefits
Your veterans guaranteed annuity works alongside existing benefits seamlessly. Moreover, An annuity is separate from VA benefits, but its tax treatment, ownership, withdrawals, and income may matter to an individual's overall financial and program situation. VA, Medicare/TRICARE, Medicaid, tax, and other rules differ; review the specific contract and consult the appropriate benefits or tax professional before acting. We do not determine eligibility or benefit amounts. Furthermore, the guaranteed nature of MYGAs means you never have to worry about market downturns affecting your retirement income.
Perfect for Veterans Who:
- Want guaranteed growth without market volatility
- Have savings in low-yield bank accounts
- Seek tax-advantaged retirement income
- Need predictable returns for financial planning
- Value principal protection above all else
Fixed Annuity Rates Veterans Can Lock In Today
Current fixed annuity rates veterans access through our service exceed most traditional investments. In fact, according to Bankrate's CD rate analysis, Remove generalized performance comparisons: a MYGA may be higher or lower than a selected CD at the time of comparison. Compare a dated offer and CD using the same term, rate convention, deposit amount, state, liquidity assumptions, taxes, and insurer or bank guarantees.
Additionally, the Federal Reserve's recent rate decisions impact fixed annuity returns significantly. Therefore, learn more about Federal Reserve interest rate policies affecting retirement savings. Meanwhile, current rates remain attractive for those ready to lock in guaranteed returns.
Frequently Asked Questions: Fixed Annuity for Veterans
What is a fixed annuity for veterans?
A fixed annuity for veterans is a Multi-Year Guaranteed Annuity (MYGA) offering guaranteed interest rates. Consequently, veterans use these products for safe, predictable retirement growth. Additionally, the principal protection makes them ideal for conservative investors.
How does a MYGA for veterans work?
Initially, you deposit a lump sum with an insurance company. Subsequently, they guarantee a fixed interest rate for your chosen term. As a result, your money grows tax-deferred until withdrawal. Furthermore, this predictable growth helps with retirement planning.
Are veterans guaranteed annuity rates really guaranteed?
A contract generally fixes its stated guaranteed interest rate for the guarantee period, subject to the contract's terms; this does not eliminate insurer credit risk or charges or adjustments triggered by withdrawals or surrender. Review the issuing insurer, minimum guaranteed rate, and contract provisions before acting.
Can I access my money in a tax deferred annuity?
A penalty-free withdrawal amount is product-specific—often, but not always, up to a stated percentage. Full surrender before term-end may incur charges or market value adjustments; confirm the exact amount, timing, tax consequences, and exceptions in the contract. Additionally, emergency access provisions vary by contract. Nevertheless, the flexibility exists for unexpected needs.
Do fixed annuity rates for veterans beat inflation?
A nominal fixed rate may be above or below inflation over the term. Do not assume a dated rate will beat future inflation; purchasing power can fall because fixed rates do not automatically adjust. Nevertheless, fixed rates provide certainty, though they don't adjust with changing economic conditions. Ultimately, the guaranteed nature provides peace of mind despite market fluctuations.
Get Your Personalized Fixed Annuity Quote
Ready to secure your annuity for veterans? Therefore, Chris Duncan, RICP®, helps veterans nationwide maximize retirement savings with MYGAs. Moreover, our personalized approach ensures you find the perfect solution for your specific needs. Ultimately, securing guaranteed returns has never been easier.
Why Veterans Trust Chris Duncan with Fixed Annuities
- ✔️ RICP® certified retirement specialist dedicated to veteran guaranteed income solutions
- ✔️ Licensed in all 50 states
- ✔️ Our services are always free to veterans
- ✔️ "We Speak Veteran®" - Understanding your unique needs
Important Disclosures:
*Rates shown are illustrative as of December 2025 and subject to change. Actual rates vary by insurer, state, and premium amount. Guarantees are based on the claims-paying ability of the issuing insurance company. Not FDIC/NCUA insured. May lose value if surrendered early. No bank guarantee. Not a deposit. Early withdrawals beyond the penalty-free amount may be subject to surrender charges and market value adjustments. This is a solicitation of insurance. Consult your tax advisor for guidance.
*Retirement Income Certified Professional® and RICP® are registered trademarks of The American College of Financial Services.
Veterans Advantage Financial® | Christopher Duncan, RICP® | Licensed in 50 States | Privacy Policy | Terms of Service